


Forty-eight hours. That’s the window where most crash claims are quietly won or lost, long before anyone files a single document. I’ve watched this play out enough times to say it plainly: the version of your story that exists two days after the crash is usually the version that sticks.
You walk away from a fender bender feeling fine, skip the paperwork, maybe swap numbers with the other driver. A week later your neck is stiff and the insurance adjuster is asking why you waited. That gap is where claims go to die. A good personal injury attorney will tell you the same thing before you even finish describing the accident, and it’s worth hearing early rather than after the letters start arriving.
Here’s what actually matters in those two days, and why the small decisions you make while still shaken carry so much weight later.
The clock starts the second the bumper touches
Insurance companies think in timelines. They log when you reported the crash, when you first mentioned pain, and when you called a lawyer. Every one of those timestamps becomes ammunition if your story shifts later. You don’t need to be paranoid. You just need to understand that a calm, documented twenty-four hours beats a messy week of guesswork every single time.
The trap most people fall into is self-editing. You tell the officer you’re fine because you don’t want to make a scene. You tell the adjuster the damage looks minor because you’re trying to be reasonable. Then the medical bill arrives and suddenly you’re the person who “said they weren’t hurt.” Those words follow you.
What to do in the first twenty-four hours
This is the part you can actually control, so treat it like a checklist and move through it fast, even if you feel fine.
- Call the police and get a report number. A report creates an independent record that doesn’t depend on anyone’s memory.
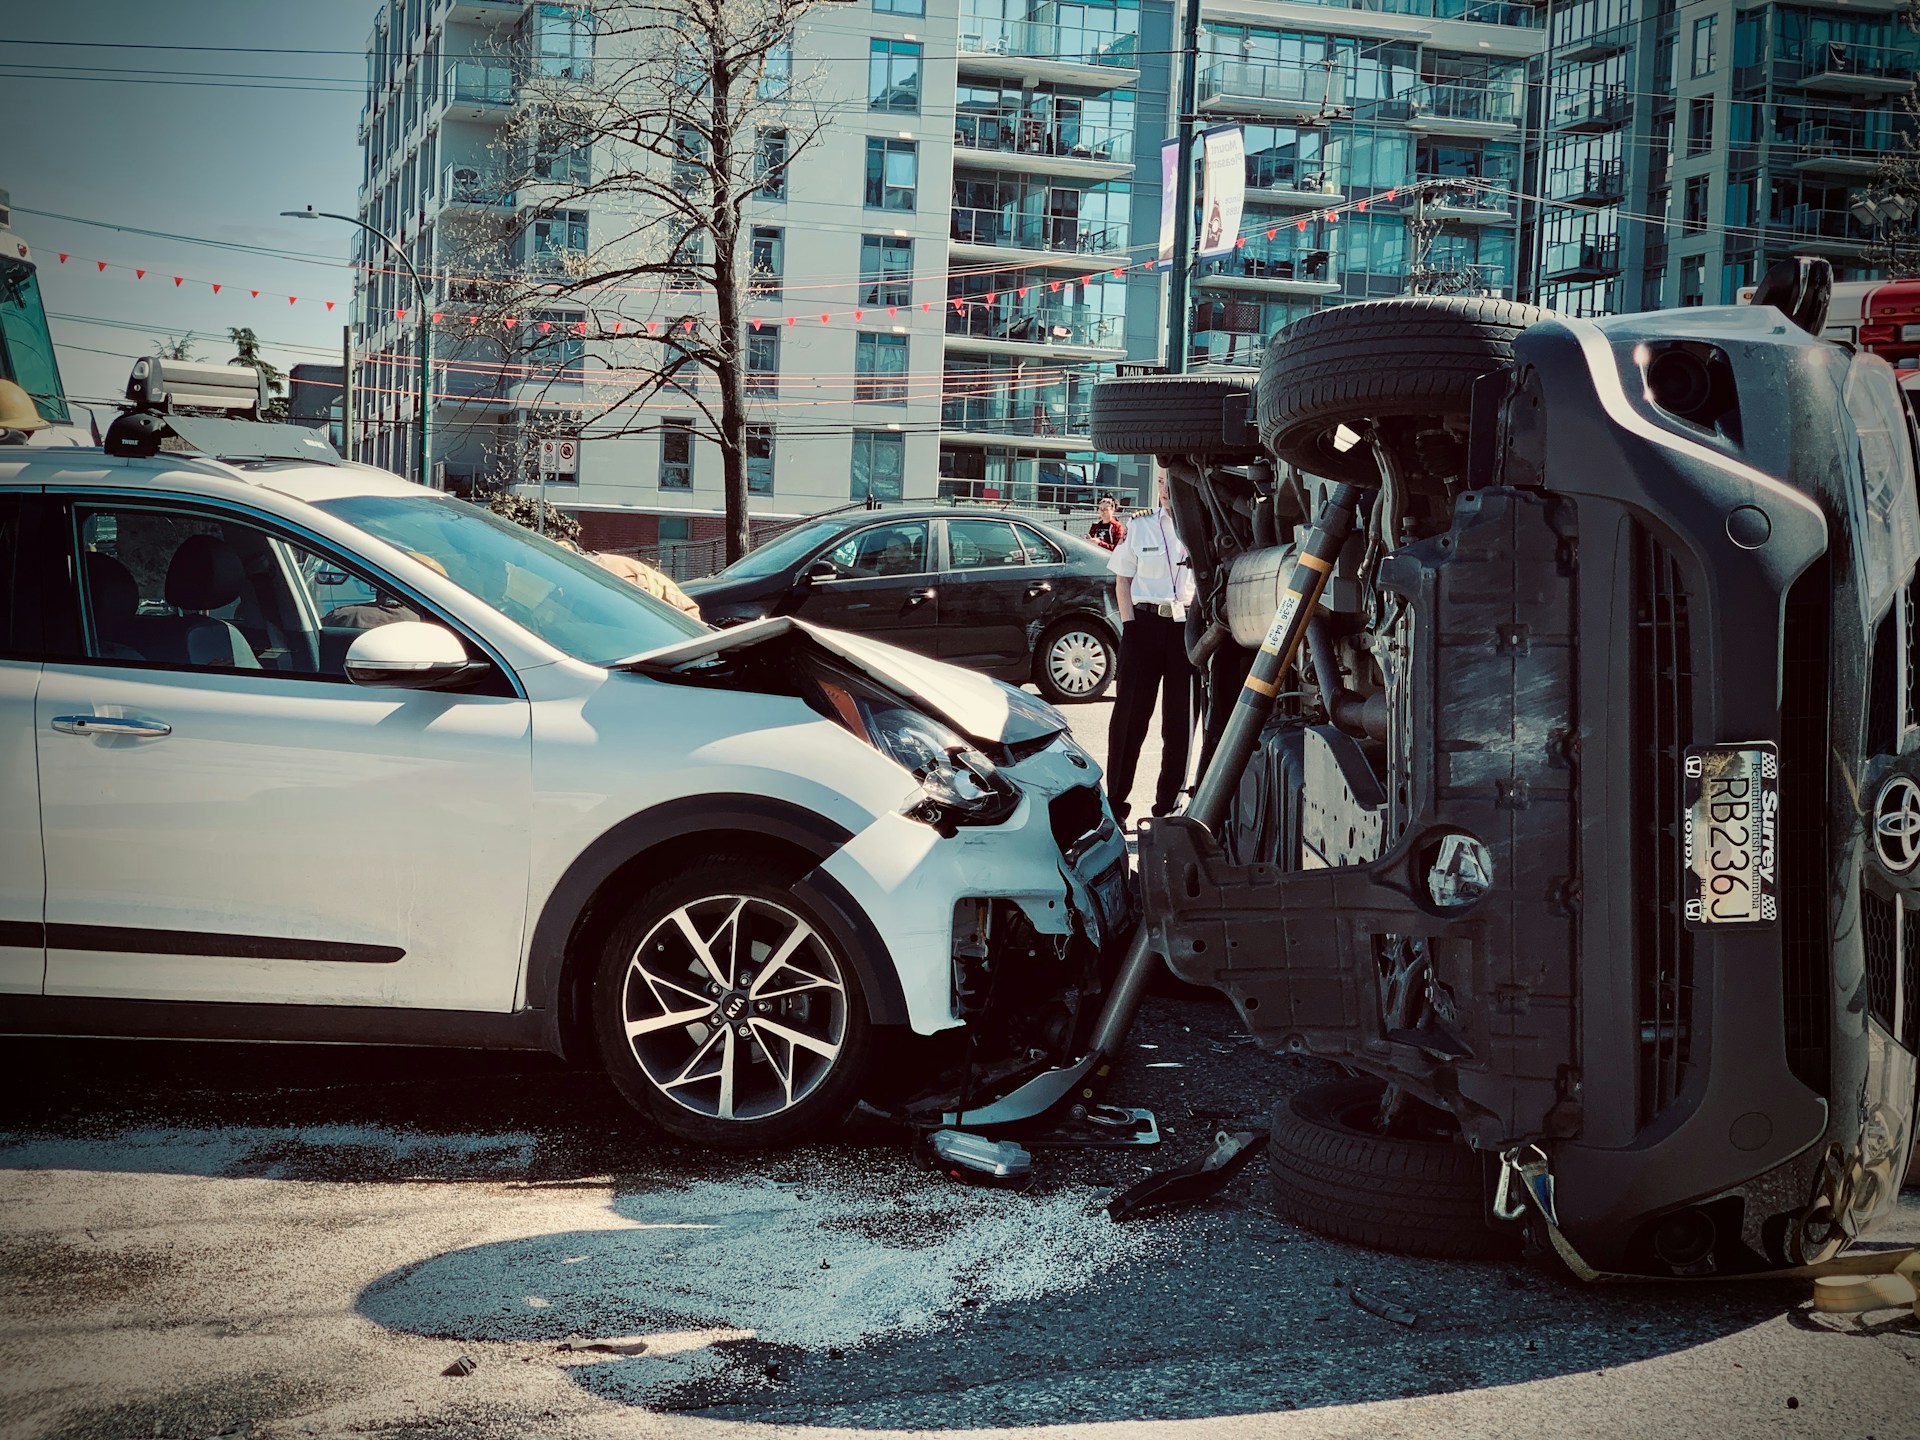
- Photograph everything. The cars from four angles, the road, the light, the skid marks, your own bruises if any show up. Your phone is your best witness.
- Collect names and numbers. The other driver, any passengers, and at least one bystander who saw what happened.
- Skip the roadside apology. Don’t say “my fault” or “I didn’t see you,” even if you think you mean it. Let the evidence sort out fault later.
- Tell your own insurer, briefly. Report the crash factually. Don’t speculate about injuries or blame.
Notice what’s missing from that list: a number. You don’t need to estimate damage or injuries on day one. You need a clean record you can build on.
Why the medical piece is trickier than it looks
Here’s where I’ll push back on the usual advice. People hear “see a doctor immediately” and assume a quick clinic visit closes the loop. It doesn’t. Some injuries, especially soft tissue and spine issues, take days to fully surface. Go get checked, but also keep a simple log of how you feel each morning for the first week. That log becomes evidence, and it’s the kind of thing nobody can recreate after the fact.
Keep every receipt, every discharge paper, every pharmacy slip. Insurance adjusters respond to organized files. Disorganized claimants get lowballed, and it’s almost never because their injury was minor.
Should you call a lawyer on day one?
Not always, but sooner than most people do. If there’s an obvious injury, a commercial vehicle involved, or the other driver is disputing fault, get a consultation early. Most injury firms offer free case reviews, so the cost of asking is basically your time. The cost of waiting is leverage you can’t get back.
One detail worth knowing: federal courts publish detailed data on how civil cases move through the system, and the volume is enormous. According to the Administrative Office of the U.S. Courts, personal injury suits make up a large share of the civil docket nationwide. That’s a polite way of saying you’re not the first person to face this, and the process has a rhythm you can prepare for.
The evidence that disappears fastest
Video is the silent killer of weak claims and the quiet hero of strong ones. Store cameras, doorbell footage, and dash cams get overwritten on rolling schedules, sometimes within days. If you remember a business near the crash site, send a written preservation request now. Don’t wait for a lawyer to do it next month.
Witness memory fades too, faster than people expect. A friendly bystander who saw everything on Tuesday may remember half of it by Friday. Get their statement in writing while it’s fresh.
Where crash data fits in
I’m a big believer in grounding a claim in real numbers rather than vibes. The Insurance Institute for Highway Safety tracks crash and fatality patterns across the country, and its research is a useful reality check when you’re wondering whether your situation is unusual. Often it isn’t. That’s reassuring, because it means there’s a well-worn path through the process.
Honest take on the timeline
If I had to boil the first two days down to one rule, it would be this: document like a pessimist, decide like a grown-up. Assume the other side will dispute everything, then act calmly anyway. The people who handle crashes best aren’t the loudest or the most aggressive. They’re the ones who keep a folder, write things down, and ask for help before the clock runs out.
What happens after the window closes
You can still build a strong case on day ten, or day thirty. Plenty of people do. But you’ll be working uphill, reconstructing details that could have been captured in an afternoon. The first forty-eight hours aren’t a deadline so much as a head start, and head starts are worth taking.
So here’s the question worth sitting with: if something happened tomorrow, would you know exactly what to do in the first hour? If the answer is a shrug, build the checklist now. Your future self, and possibly your claim, will thank you.