

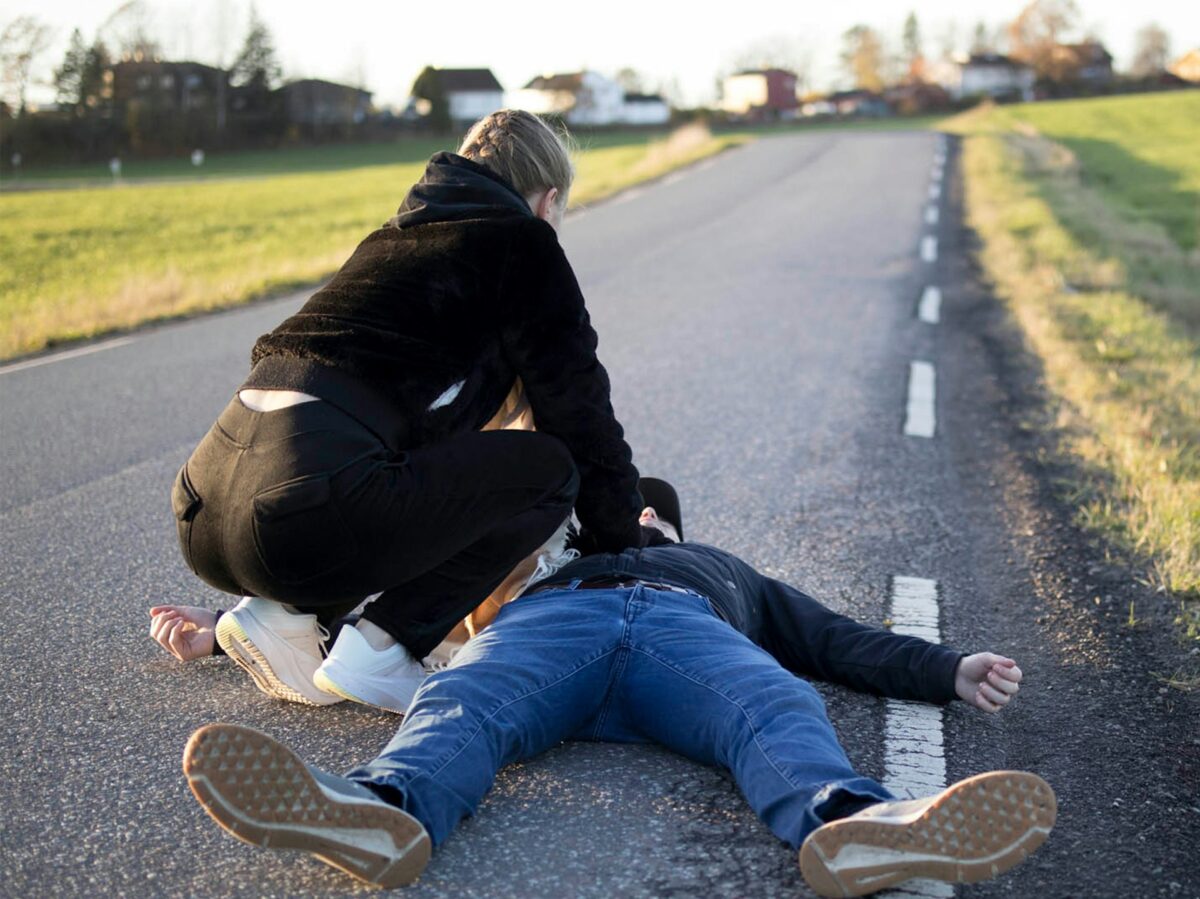

An accident in Ontario can leave an injured person dealing with unfamiliar decisions at a time when attention is already focused on recovery.
Insurance correspondence, collision questions, and requests for information can arrive while medical care and everyday responsibilities still demand attention.
One of the more significant requests may be an invitation to provide a recorded statement. Understanding what that request means before responding can help an injured person approach the conversation carefully and keep the claim facts clear.
For people facing a personal injury claim, speaking with a personal injury lawyer in Ontario, CA can provide useful guidance before an insurance interview takes place. A lawyer can review the accident circumstances, explain the purpose of the request, and help identify which details may require particular care when discussed with an insurer. Understanding the situation beforehand can help the claimant respond accurately and avoid unnecessary confusion during the claims process.
When A Claimant Should Respond
A claimant should not assume that every request requires an immediate interview. The answer depends on who requested the statement and the insurance policy involved.
The at-fault driver’s insurer has no automatic right to question an injured claimant. That insurer is gathering evidence for its own investigation, so the claimant should seek legal advice before agreeing to a recorded interview.
The claimant’s own insurer may have contractual duties under a policy, particularly after an uninsured-motorist or underinsured-motorist collision. The policy language and applicable state law matter. Refusing without advice can create coverage problems, while answering without preparation can create factual problems.
People handling serious injuries, disputed liability, or multiple vehicles should consider speaking with a personal injury lawyer in Ontario before providing a recording. Legal guidance helps clarify the interview’s purpose, ensure facts are accurate, and prevent unrelated questions from derailing the discussion. A lawyer can also address requests involving prior accidents, medical history, employment, or social activities when those subjects require careful context.
Why Insurers Request Recorded Statements
Insurance companies use recorded statements to collect facts before deciding whether to accept, reduce, or deny a claim. The adjuster usually asks about the accident, symptoms, medical care, work absence, and prior injuries.
The recording creates a permanent account of the event. If later testimony differs, the insurer can use the earlier statement to question the claimant’s reliability. Even an innocent mistake about timing or symptoms can become part of the claim file.
An adjuster also listens for comments about fault. Saying that a claimant “did not see” another vehicle, “felt fine” immediately afterward, or “could have avoided” the incident can support an argument that reduces responsibility.
How Statements Can Affect Claim Value
A recorded statement can affect the value assigned to physical injuries. Some symptoms appear hours or days after a collision, especially with soft-tissue injuries or head trauma. Saying that no pain existed at the scene does not prove that an injury was absent, but an insurer can use that answer to dispute causation.
The same concern applies to medical treatment. Delayed appointments, missed visits, or gaps in care often invite questions about whether the injury remains serious. A claimant should explain those facts accurately without guessing or minimizing symptoms.
Work-related information also receives close attention. An adjuster may ask when the claimant returned to work, what tasks remained difficult, and whether wages were lost. Exact records are safer than estimates because inconsistent figures can weaken a lost-income claim.
How To Prepare For The Interview
Preparation starts with reviewing the accident report, photographs, medical records, appointment dates, and wage information. The claimant should separate confirmed facts from assumptions and avoid filling gaps with guesses.
Answers should remain direct and truthful. “I do not remember” is more accurate than inventing a time, speed, distance, or sequence. The claimant should describe symptoms as they existed, including changes after the accident.
A claimant should also avoid broad statements. Saying that an injury affects “everything” or that someone is “always” in pain invites follow-up questions and possible contradictions. Specific examples provide clearer evidence, such as difficulty lifting a child, driving, standing, or completing assigned work.
The interview should take place in a quiet setting without interruptions. The claimant should listen to each question, pause before answering, and request clarification when the wording is unclear. No one should sign a transcript or statement without reading it carefully.
Common Mistakes That Create Problems
One mistake involves volunteering unrelated information. An adjuster may ask a narrow question, but a long answer can introduce details that later require explanation.
Another mistake involves speculating about fault. Claimants often know what they observed, but they cannot know another person’s speed, attention, or intentions without evidence. Describing observations is safer than assigning motives.
Claimants should also avoid discussing settlement expectations during a recorded statement. The interview concerns facts, not the amount of compensation sought. Medical prognosis, future treatment, and permanent limitations require information from qualified providers.
Conclusion
A recorded statement can shape an insurer’s view of liability, injury severity, treatment, and lost income. Claimants protect their position by reviewing records, answering only what they know, and avoiding guesses or broad conclusions. The safest next step is to identify which insurer requested the interview and whether a policy requires cooperation. Before speaking, an injured person should obtain legal advice when fault, serious injuries, or coverage questions could affect the claim’s value.